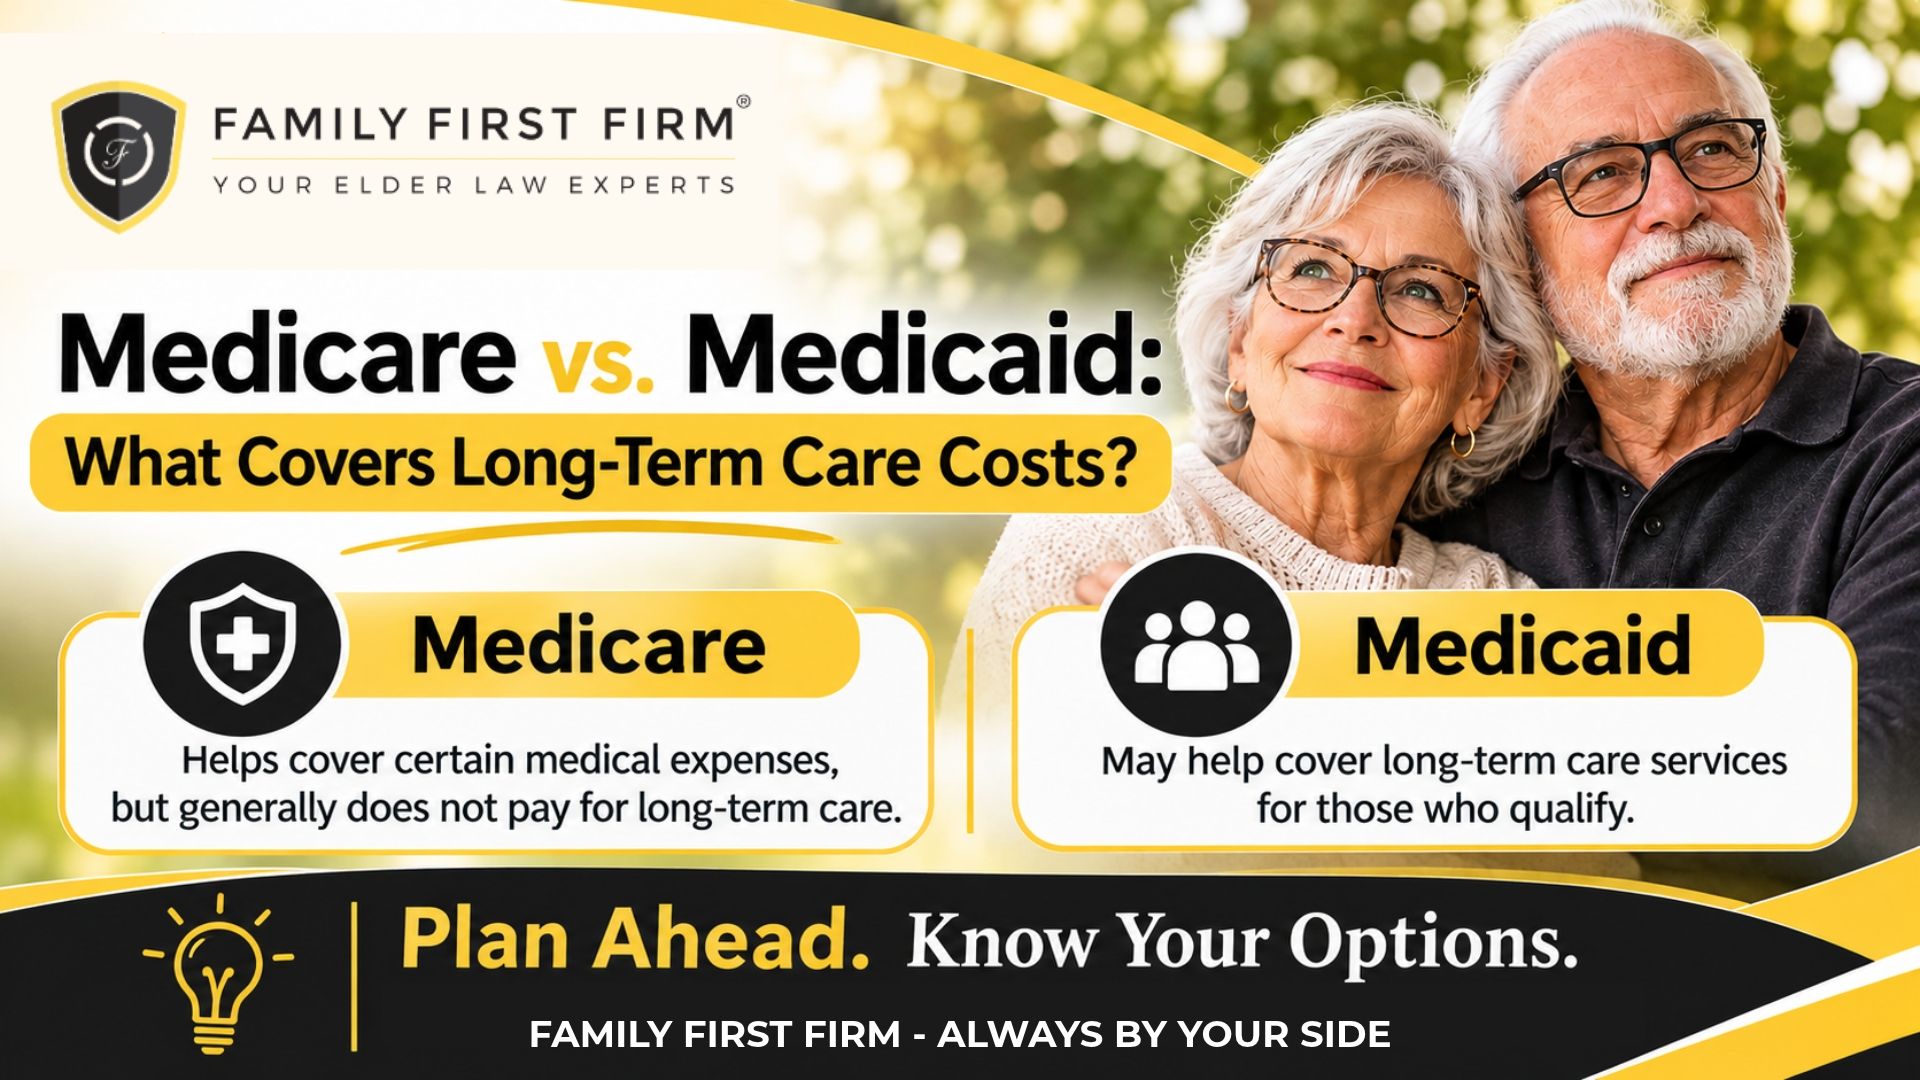
When a loved one needs help with everyday activities, requires ongoing supervision, or can no longer live safely at home, families often incorrectly assume that Medicare will pay for long-term care.
Although their names sound similar, Medicare and Medicaid serve different purposes. Understanding how each program works can help families prepare for the cost of care, avoid unexpected expenses, and make informed decisions about their future.
At Family First Firm, we help families understand the role Medicaid can play in long-term care planning and explore options based on their individual circumstances.
What Is the Difference Between Medicare and Medicaid?
Medicare is a federal health insurance program primarily for people age 65 and older, as well as certain younger people with disabilities or specific medical conditions. It helps cover eligible medical expenses, including hospital stays, doctor visits, prescription medications, and certain short-term skilled nursing services.
Medicaid is a joint federal and state program that provides health coverage to people who meet applicable eligibility requirements. For eligible individuals, Medicaid can also help pay for long-term care services that Medicare generally does not cover, including qualifying nursing home care and certain home and community-based services.
The distinction becomes especially important when someone needs care for an extended period rather than help recovering from an illness, injury, or surgery.
Does Medicare Pay for Long-Term Care?
One of the most common misconceptions about Medicare is that it will cover the cost of a nursing home if a person needs care as they age.
In reality, Medicare generally does not pay for long-term care.
Long-term care is assistance with everyday activities such as:
- Bathing and getting dressed
- Eating and personal hygiene
- Using the bathroom
- Moving safely from a bed to a chair
- Receiving ongoing supervision or assistance with daily routines
A person may need this type of care because of dementia, mobility challenges, a chronic illness, or the general effects of aging. Even when care is medically necessary for the person’s safety and well-being, that does not automatically mean Medicare will cover it.
What Medicare may cover
Medicare may cover qualifying short-term care in a Medicare-certified skilled nursing facility when a person meets the program’s requirements. This can include skilled nursing services and rehabilitation following a qualifying hospital stay.
Eligible beneficiaries may receive up to 100 days of skilled nursing facility care in a benefit period. Coverage is subject to specific conditions and cost-sharing requirements. The first 20 days generally have no daily coinsurance after applicable deductible requirements; days 21–100 have daily coinsurance, and the beneficiary pays all costs after day 100.
Medicare may also cover certain medically necessary home health services, physician visits, and therapies when coverage requirements are met. However, these benefits are not the same as ongoing assistance with daily living.
The important takeaway: Medicare may help pay for qualifying short-term skilled care, but families should not assume it will cover months or years of ongoing personal care.
What Does Medicaid Cover for Long-Term Care?
For individuals who meet the applicable eligibility requirements, Medicaid may help cover long-term care costs that Medicare does not. Services may include:
- Nursing home care: Qualifying nursing facility services for people who meet the program’s medical and financial requirements.
- Home- and community-based services: Certain services that help eligible individuals receive care while living at home or in the community.
- Personal care assistance: Help with qualifying daily activities, depending on the program and approved services.
Coverage is not automatic. Applicants must meet financial eligibility rules and medical or functional requirements. The exact rules, covered services, and availability of programs vary by state.
How does Medicaid work in Florida?
Florida evaluates both financial eligibility and medical eligibility for long-term care services. The program also has a screening and prioritization process, and access to certain community-based services may involve a waiting list.
That means families should not assume that qualifying financially guarantees immediate access to every service they may need. Learning about eligibility and available options early can help families plan more effectively.
A person may qualify for both Medicare and Medicaid. In these situations, Medicare generally pays first for covered Medicare services, while Medicaid may help with eligible additional costs and services, depending on the person’s coverage. Source: Medicare.gov
How Do Families Pay for Long-Term Care When Medicare Doesn’t Cover It?
The cost of care can place considerable pressure on a household, particularly when one spouse needs care and the other still needs money to maintain a home and cover living expenses.
This is one reason families should consider long-term care planning before a crisis occurs. Waiting until care is urgently needed can leave fewer practical options and make decisions more stressful.
Family First Firm Can Help You Qualify, Even With Assets
Many people assume that having a home, savings, or retirement accounts automatically disqualifies them from Medicaid long-term care benefits. That is not the case.
The best time to learn about long-term care options is generally before an immediate need arises.
Understanding the complexities of long-term care planning can help families avoid a costly surprise and prepare for the financial realities of aging.
At Family First Firm, we help families explore Medicaid eligibility and long-term care planning options based on their individual circumstances. If you are concerned about the cost of care for yourself or a loved one, learning about your options early can make a meaningful difference.
Contact Family First Firm to discuss your long-term care planning questions and learn what options may be available for your family.